Coming to the United States with the ambition of building a better life does not automatically lead to financial security.
For many immigrants, the first few years can feel paradoxical.
You work. You earn a paycheck. You pay rent. You buy a car. You may support family members back home. Little by little, you begin building a new life.
And yet, at the end of every month, there is almost nothing left.
The paycheck arrives, the bills get paid, and then you wait for the next paycheck.
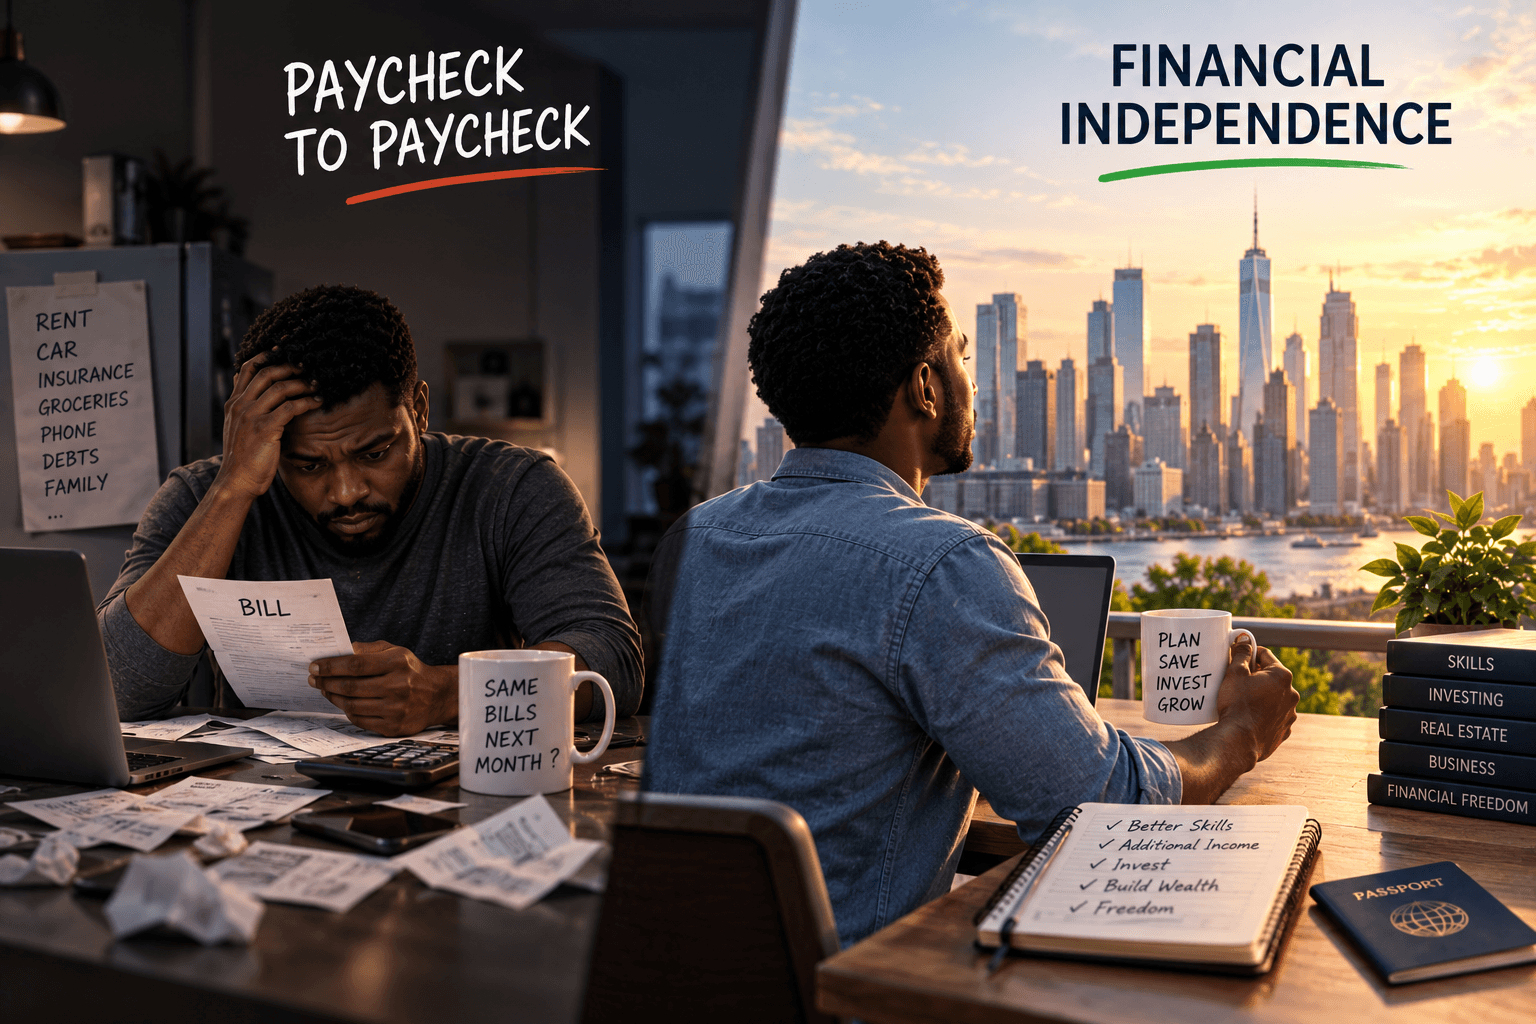
This is what Americans call living “paycheck to paycheck.”
For some immigrants, this cycle can continue for five, ten, fifteen years, or even longer.
The real question then becomes:
How do we move from simply surviving financially to building true financial independence?
Earning Money Is Not the Same as Building Wealth
This may be one of the first important lessons to understand.
Someone can earn $60,000, $80,000, or even $100,000 a year and still remain financially vulnerable.
Why?
Because income is only one part of the equation.
If nearly everything we earn immediately goes toward housing, cars, credit cards, insurance, subscriptions, family obligations, and other expenses, our salary can increase without our actual wealth increasing.
Financial independence begins when our money is no longer used only to finance today's lifestyle but also starts to build tomorrow's future.
The “I Finally Made It” Trap
When you come from an environment where certain things may have been difficult to access, arriving in the United States can create a unique feeling.
For the first time, it may become possible to finance a nice car, buy furniture on credit, use several credit cards, get the latest phone through monthly payments, rent a larger home, or travel more frequently.
None of these things are necessarily bad.
The problem begins when our lifestyle grows just as quickly as our income.
Every raise creates a new expense.
This is often called lifestyle inflation: the more we earn, the more we spend.
Years later, we may be earning significantly more than when we first arrived, yet our financial situation has barely changed.
The Financial Responsibility of Supporting Family
The financial reality of many African immigrants can also be different from that of the average American household.
Our income may not support only the people living under our roof.
It may also help parents, pay a sibling's school fees, contribute to funerals, cover medical expenses, support a family construction project, or respond to emergencies back home.
This solidarity is an important value in many of our communities.
But it can become financially difficult when there are no boundaries.
We cannot sustainably support everyone else while our own financial situation remains constantly fragile.
Sometimes we have to learn something that can be culturally difficult:
Create a budget for helping family.
Help according to what you can realistically afford rather than responding financially to every request.
Building your own financial stability does not mean abandoning your family.
In fact, someone who is financially stable is often in a much stronger position to help others over the long term.
First Step: Know Exactly Where Your Money Goes
One of the most powerful financial exercises is also one of the simplest.
For a few months, track everything you spend.
Not just rent and car payments.
Track restaurants, online shopping, subscriptions, money transfers, impulse purchases, apps, entertainment, gas, insurance, credit cards, phone bills, and recurring services.
Some people discover something surprising.
The problem is not always that they do not earn enough.
Sometimes, they simply do not know where their money is actually going.
A budget should not be viewed as punishment.
A budget is simply a decision made in advance about where your money should go.
Build an Emergency Fund
A large part of financial stress comes from a simple problem:
Every unexpected expense becomes a crisis.
A car repair.
A medical bill.
A temporary job loss.
An urgent family trip.
A home repair.
Without savings, the solution often becomes a credit card.
Then debt begins to accumulate.
Gradually building an emergency fund can help break that cycle.
The goal does not have to be several months of expenses immediately.
Start small.
$500.
Then $1,000.
Then one month of expenses.
Then gradually build from there.
Financial security is often created one step at a time.
Break the Cycle of Expensive Debt
Not all debt is the same.
But certain types of debt, particularly high-interest credit card debt, can become extremely difficult to eliminate when credit cards are being used every month to supplement income.
When we make only minimum payments, a significant portion of our money may go toward interest rather than reducing what we owe.
Breaking that dependence becomes a priority.
That may require temporarily reducing certain expenses, increasing income, and most importantly, avoiding new debt while paying down existing balances.
The goal is not simply to owe less money.
The goal is to recover part of our income so that it can eventually begin working for us.
American Credit: A Tool, Not Additional Income
For many new immigrants, the American credit system is completely new.
A credit card with a $10,000 limit can create the impression that you suddenly have an additional $10,000 available.
You do not.
Credit is a tool that allows you to borrow money.
Used responsibly, it can help establish a financial history that may be useful for certain transactions.
Used poorly, it can become a burden for years.
A simple rule to remember is:
A credit limit is not money you own.
Reduce Expenses — But More Importantly, Increase Income
There is a limit to how much you can cut from your expenses.
But your potential to increase your income may be much greater.
That is why one of the most important financial investments immigrants can make is:
Investing in skills.
Improve your professional English.
Earn a certification.
Return to school.
Learn a technology skill.
Move into a different industry.
Negotiate your salary.
Look for a better employer.
Learn a skilled trade.
Some immigrants can dramatically improve their financial situation by changing careers rather than trying to save an additional $100 every month.
Your skills can become one of your most valuable assets.
Do Not Stay Too Long in Your First Job
Your first job in America often has special significance.
It gives you a beginning.
But it does not have to become your final destination.
Some immigrants remain in low-paying jobs for many years simply because those employers gave them their first opportunity.
We should regularly ask ourselves:
What skill could I learn today that might significantly increase my income two or three years from now?
Does my current salary reflect the value of my experience?
Is there another industry where my skills could be better compensated?
What certification could open another door?
Economic integration also means developing the ability to evolve.
Build Multiple Sources of Income
Depending entirely on one paycheck can make a household vulnerable.
This does not mean everyone needs to start ten businesses at the same time.
But over time, some families develop several sources of income: a primary job, a side business, consulting, a small company, rental income, investments, digital activities, or professional services.
The principle is simple:
The more your entire financial life depends on one source of income, the more vulnerable you become if that source disappears.
Entrepreneurship: A Real Opportunity, But Not a Shortcut
The United States offers many opportunities to start a business.
Cleaning.
Transportation.
Construction.
Beauty.
Food services.
Technology.
Consulting.
E-commerce.
Professional services.
Real estate.
And many other industries.
For immigrants, entrepreneurship can become a powerful path toward wealth creation.
But we should avoid one illusion.
Starting a business does not automatically create financial independence.
A poorly managed business can create debt as easily as a successful one can create wealth.
Entrepreneurs need to understand the fundamentals: accounting, cash flow, marketing, taxes, contracts, insurance, pricing, profit margins, and customer management.
Entrepreneurship becomes powerful when it is treated as a real business rather than an improvisation.
Start Investing — Even If You Start Small
Many immigrants work for years without fully using some of the wealth-building opportunities available in the United States.
Employer-sponsored retirement accounts, potential employer contributions, individual retirement accounts, diversified long-term investments, and real estate when appropriate may all be options worth exploring depending on individual circumstances.
Sometimes we tell ourselves:
“I'll start investing when I have a lot of money.”
But wealth building often works in the opposite direction.
You start small.
Then you gradually increase your contributions as your income grows.
One of the hardest financial resources to recover is time.
Buying a House Is Not the Only Symbol of Success
In many communities, buying a home represents an important milestone.
And homeownership can indeed become part of building long-term wealth.
But purchasing a house that is too expensive simply to demonstrate success can have the opposite effect.
The same applies to cars.
Real wealth is not necessarily what other people can see.
Someone may drive a very expensive vehicle while having almost no savings.
Another person may drive a modest car while quietly building significant investments.
Real wealth is often much less visible than we imagine.
Understand Taxes and Plan for the Future
As income grows, understanding taxes also becomes increasingly important.
Employees, entrepreneurs, property owners, investors, and self-employed workers can have very different financial situations.
As finances become more complex, working with qualified professionals may be helpful.
Financial planning is not simply about making it through next month.
It is also about thinking about what we want to build over the next ten, twenty, or thirty years.
Protect What You Are Building
Building wealth is important.
Protecting it matters too.
Depending on your family and financial situation, that may involve appropriate insurance, estate planning, properly designated beneficiaries, protection for children, and keeping important financial documents organized.
Financial security is not only about today.
It is also about protecting the people who depend on us.
Be Careful With Shortcuts to Wealth
People who desperately want to improve their financial situation can unfortunately become ideal targets for scams.
Miracle investments.
Supposedly guaranteed cryptocurrency returns.
Trading presented as risk-free.
Pyramid schemes.
“Business opportunities” requiring large upfront payments.
Promises to quickly double your money.
Financial independence is rarely spectacular.
It is usually built through relatively simple decisions repeated consistently over a long period of time.
A Possible Roadmap
Every individual and family will have a different journey, but a reasonable path might begin with:
Understand exactly how much you earn and where your money goes.
Gradually build an emergency fund.
Prioritize eliminating expensive debt.
Continuously improve your skills and earning potential.
Build and protect your credit responsibly.
Explore available savings and retirement opportunities.
Begin investing gradually according to your circumstances and goals.
Consider developing multiple sources of income.
Protect your family and the wealth you are building.
Avoid allowing every salary increase to automatically become a lifestyle increase.
The goal is not to accomplish everything immediately.
The important thing is knowing which direction you are moving.
What Does Financial Independence Really Mean?
It does not necessarily mean becoming a millionaire.
For some people, it means being able to pay every bill without stress.
For others, it means having several months of expenses saved.
For someone else, it means being able to lose a job without immediately putting the family in financial danger.
It may mean having enough invested to prepare for retirement.
Being able to support your parents without going into debt.
Paying for your children's education.
Starting a business.
Or simply being able to choose where you work instead of remaining in a job because missing one paycheck would create a crisis.
Financial independence is ultimately about having more choices.
Financial Success Can Also Become Collective
Imagine a diaspora where people who already understand the system teach others how credit works, how to negotiate salaries, how to prepare for retirement, how to approach homeownership wisely, how to start a business, how to avoid common financial mistakes, and how to begin building wealth.
We can transform years of individual trial and error into hours of shared knowledge.
Someone who learned a lesson after ten years of mistakes may be able to help a newcomer avoid those same ten years of mistakes.
Financial knowledge can also become a form of community solidarity.
DiasporaTogo Opens the Conversation
When you first arrived in the United States, what financial lesson do you wish someone had taught you immediately?
Have you ever lived paycheck to paycheck?
What decision made the biggest difference in your financial life?
Changing careers? Paying off debt? Starting a business? Beginning to invest? Buying your first home? Learning how to better manage your money?
Share your experience in the comments.
Your journey may contain a lesson that helps someone else avoid a mistake, make a better decision, or simply realize that there is a path forward.
Our goal should not only be to earn a living in America. Over time, it should be to build a life in which our money gives us greater security, freedom, and opportunity.
This article is intended for educational and community discussion purposes. Financial circumstances vary, and significant decisions involving investments, taxes, credit, or retirement may require guidance from a qualified professional.